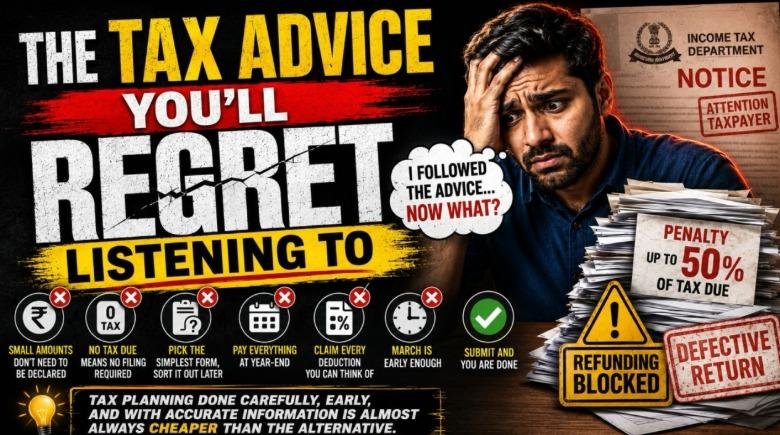
Every financial year, the vast majority of Indians walk into their tax filing with advice picked up from a colleague at lunch, a relative who files their own returns, or a thread they half-read online. Some of it is harmless. Some of it results in a notice from the Income Tax Department.
Here are the ones worth unlearning.
Small amounts don’t need to be declared
Every source of income needs to appear in your ITR savings account whether it’s interest, freelance payments, rental income, or online gaming winnings.
The AIS already captures most of it. When what you declare does not match what the department sees, that mismatch is flagged automatically.
Penalties for underreporting can go up to 50% of the tax due. The amount being small does not make the omission smaller.
No tax due means no filing required
Filing an ITR goes beyond just paying tax. Banks ask for it when you apply for a loan. Passport applications sometimes require it. Refunds cannot be processed without a filed return. Skipping it also invites scrutiny and blocks any credits you might be owed. Zero tax liability is not the same as zero obligation.
Pick the simplest form, sort it out later
Filing on the wrong ITR form creates a defective return. Miss the correction window and the return is invalid. Refunds denied, losses forfeited, not pretty!
For taxpayers with foreign assets who file on a simplified form, the consequences fall under the Black Money Act, where intent is not a defence.
Pay everything at year-end
If your total tax liability crosses ₹10,000, advance tax applies across four deadlines: June 15, September 15, December 15, and March 15. Missing any of these attracts interest of 1 to 1.5% per month on the unpaid amount. It is not catastrophic per payment. Across multiple missed quarters it adds up to a bill that was entirely avoidable.
Claim every deduction you can think of
Deductions require documentation. Fake or unsupported claims are disallowed during assessment, and penalties can reach 200% of the tax on the falsely claimed amount. If you cannot produce the proof, do not claim it.
March is early enough
Every year, the same scramble. Investments rushed, forms selected in a hurry, deductions missed because pressure left no room to think. An ELSS investment made in April compounds for twelve months. The same investment made in March compounds for one. That difference, repeated over years, is not trivial.
Submit and you are done
Filing is not the finish line. An unverified ITR is treated as if it was never submitted. E-verification must be completed within 30 days of filing, through net banking, Aadhaar OTP, or the EVC process. One step skipped and the entire return is invalid.
The common thread across all of these is the same. Tax planning done carefully, early, and with accurate information is almost always cheaper than the alternative.